Your First Home: a helping hand for buyers or a boost for housebuilders?
Unveiled just ahead of the Labour Party Conference in Liverpool, the Government’s new ‘Your First Home’ scheme raises some interesting questions.
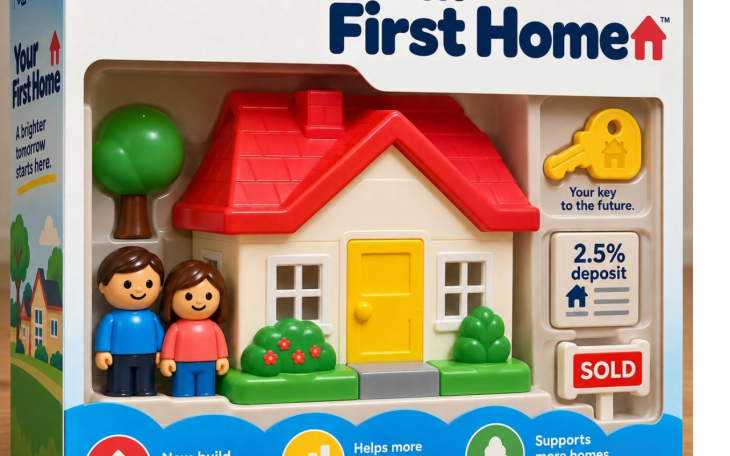
What we know so far is that it is a Government equity loan initiative in England designed to help first-time buyers purchase new-build properties with a low deposit of 2.5%. Firm details will be released as part of the Budget announcement next month.
On the positive side, a 2.5% deposit could make a real difference to people who can afford the monthly cost of home ownership but struggle to save the upfront capital. The 20% equity loan also reduces the size of mortgage buyers need to secure.
And, by restricting the scheme to new-build homes, there is the potential for a wider impact on housing delivery. More eligible buyers should mean faster sales, which could improve viability, help unlock stalled or marginal sites and give developers greater confidence to build out existing sites and invest in new ones.
There are some useful lessons from Help to Buy. The Government's recently published evaluation estimates that around 15% of new homes built during the scheme were additional, but also found evidence that the scheme increased prices and that a significant proportion of buyers could have purchased without it.
There are, however, some big questions still to answer:
Can supply respond quickly enough? If purchasing power increases faster than the number of homes being built, some of the benefit could end up in higher prices, developer margins and ultimately land values.
How much additionality will it actually create? Will it enable people to buy who otherwise couldn't, or will some recipients simply buy sooner or spend more than they otherwise would have?
Does it address the real affordability problem? A smaller deposit helps if saving the deposit is the barrier. It does much less if your income simply won't support the mortgage required to buy where you live.
What happens to buyers further down the line? Starting with just 2.5% of your own equity doesn't leave much of a cushion if prices fall, while the precise terms of the Government's equity stake and what happens after the initial interest-free period are still to be confirmed.
How quickly can the industry respond? Increasing demand doesn't instantly restore capacity or reverse decisions already taken to slow build-out, reduce investment or acquire less land.
Much of the detail, including household income limits, local property price caps, developer contributions and implementation, will come at the Budget.
Instinctively, this feels more like an intervention designed to stimulate the housebuilding market and less like a policy specifically about getting people onto the housing ladder. Which isn't necessarily a bad thing, if it gets more homes built.
What to read next
Browse below for the latest news, insights and thought leadership from our team of experts
Going for the Grid: Burnham tries to take back control
Solar and Storage Live: The shift from tick-box consultation to meaningful engagement
Burnham goes big in first conference speech, but real test still lies ahead at the Budget
Why dark social matters more than ever
Corporate affairs and navigating dystopia
The new reputation battlefield: Navigating risk in a fragmented media landscape
Investors ponder what's next in property
Abundant energy at Climate Week NYC